When Playing It Safe Becomes Risky
Finding the balance between protecting what you've built and preparing for what's ahead.
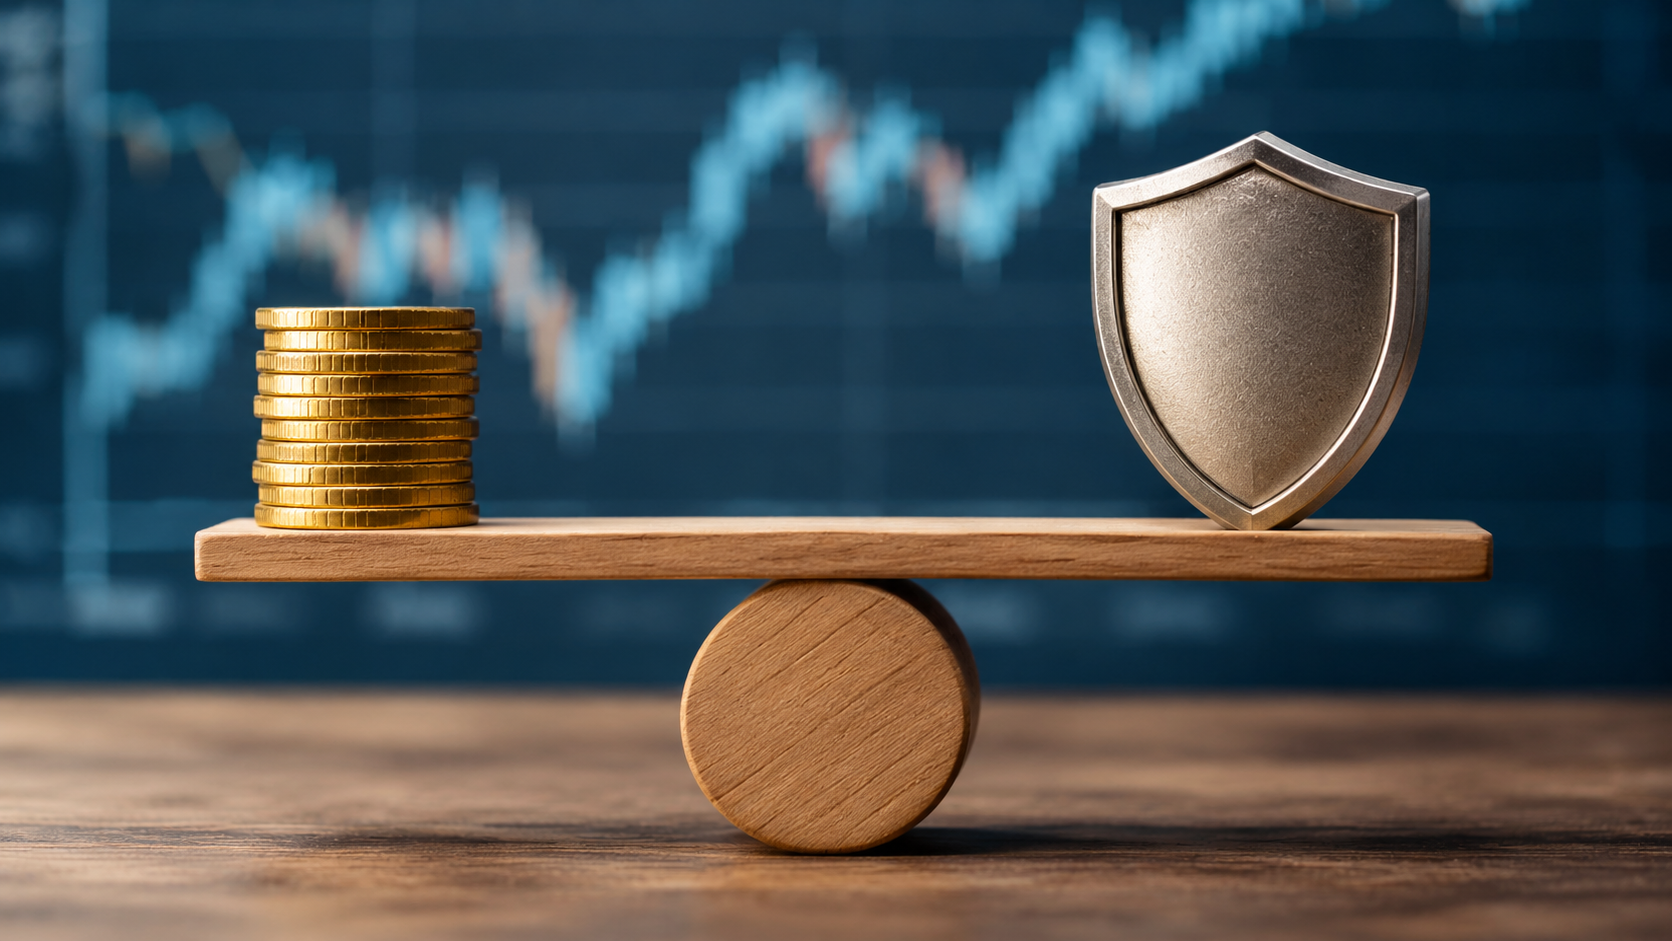
There's a reason people talk about playing it safe with their money. After years of working, saving, and building wealth, protecting what you've earned is a natural priority.
A conservative approach to investing can offer stability, reduce exposure to market volatility, and help provide peace of mind. And depending on your circumstances, that may be exactly what your financial plan needs.
But financial security isn't necessarily about avoiding risk altogether. Sometimes, it's about understanding how different types of risk affect your financial goals.
The challenge is finding the balance between protecting what you have today and preparing for what you'll need tomorrow.
The Different Sides of Financial Risk
When most people think about investment risk, they picture the stock market. Falling prices, unpredictable headlines, and fluctuating account balances are all visible reminders that investing involves uncertainty.
But market volatility isn't the only type of financial risk.
Inflation, for example, can gradually reduce the purchasing power of money over time. While a savings account or other cash holding may maintain a relatively steady balance, the amount of goods and services that money can purchase may change.
Consider a hypothetical $100,000 held in cash for 25 years. Assuming the balance earns no interest and inflation averages 3% annually, its purchasing power would decline to the equivalent of approximately $48,000 in today's dollars.
The account balance hasn't changed, but its purchasing power has.
This doesn't mean holding cash is a poor decision. Cash plays an important role in maintaining liquidity, covering unexpected expenses, and providing financial flexibility.
It simply illustrates that different financial strategies protect against different types of risk.
Time Changes the Conversation
One of the most important considerations in managing investment risk is time.
Money intended for a major purchase next year serves a very different purpose than money designated for retirement 20 years from now.
For shorter-term goals, stability and accessibility may take priority over potential investment growth. For longer-term goals, the ability to grow wealth and keep pace with inflation may become increasingly important.
The same principle applies throughout retirement.
Someone approaching retirement may prioritize protecting the money they'll need in the coming years while maintaining opportunities for growth in assets intended to support later stages of life.
Rather than viewing an entire portfolio as either conservative or aggressive, it can be helpful to consider the purpose and timeline of different assets.
Finding Comfort in a Thoughtful Strategy
There's also an emotional component to investing.
Market volatility can be uncomfortable, particularly when the money involved represents decades of hard work. It's understandable to prefer investments that feel stable and predictable.
But financial confidence doesn't have to come from eliminating uncertainty.
It can come from understanding why certain investments are included in a portfolio, what purpose they serve, and how they fit into a larger financial strategy.
A written financial plan can provide a valuable reference point during periods of market volatility. Instead of reacting to individual headlines, investors can revisit their goals, time horizons, and overall strategy.
Knowing what you own and why you own it is an important part of maintaining investment discipline
Balancing Growth and Protection
Ultimately, there's no universal definition of playing it safe.
For one individual, a conservative allocation may be appropriate for an upcoming financial obligation. For another, pursuing long-term growth may be essential to supporting decades of retirement expenses.
Neither approach is inherently right or wrong. What matters is how each decision supports the broader financial picture.
Because the goal is to develop a thoughtful strategy that balances both in a way that aligns with the life you're planning to live.
At Prestige Advisors, financial planning begins with understanding the purpose behind your wealth, from near-term needs to long-term aspirations. If you're ready to take a more coordinated approach to your tax and financial planning, contact us at hello@prestigeadvisors.com to schedule a complimentary introductory conversation.
Disclosure: This content is for educational and informational purposes only. It does not constitute investment, financial, tax, or legal advice, and nothing here should be interpreted as a recommendation to buy or sell any security or pursue any specific strategy. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Any hypothetical examples are for illustrative purposes only and do not reflect actual investment results. The inflation example assumes a constant 3% annual inflation rate and no interest or investment growth; actual inflation rates and outcomes may vary. Tax laws are complex and apply differently to each person’s situation. Consult your own qualified tax, legal, and financial professionals before making any decisions.