A Financial Frankenstein: When the Pieces of Your Plan Don’t Work Together
Avoid a “Financial Frankenstein.” Even the right financial pieces need coordination to work together effectively.
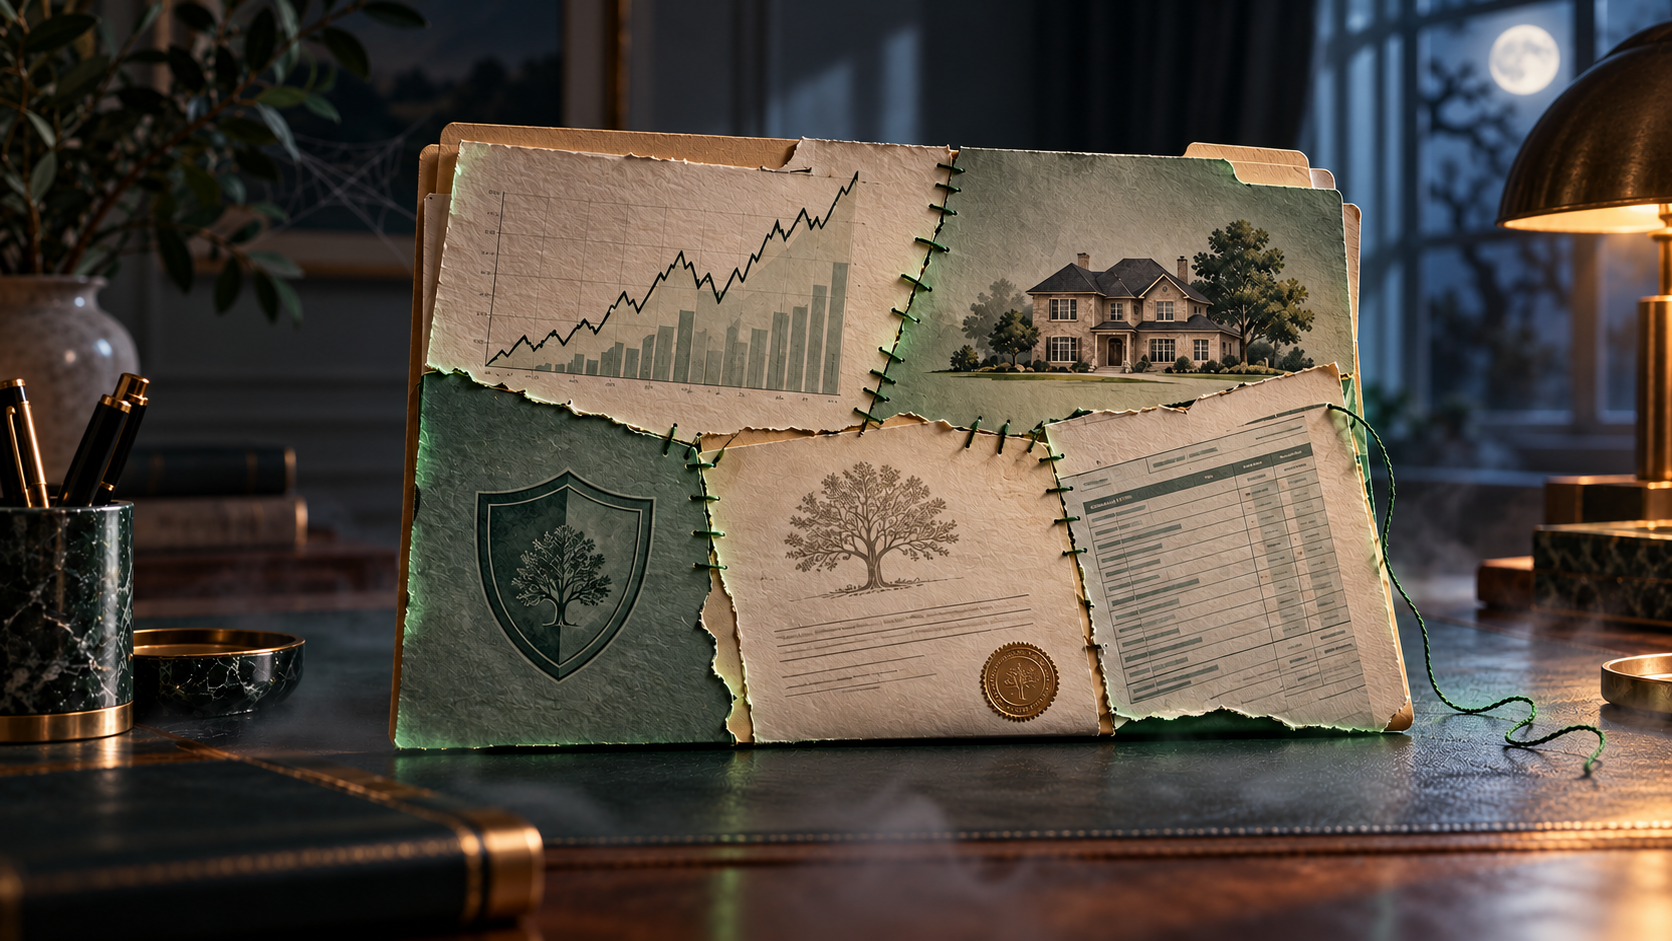
You have investments, life insurance, an estate plan, and a CPA who handles your taxes. If you own a business, you may also have a succession strategy taking shape.
On paper, you’ve covered a lot of ground. You’ve sought professional advice and made thoughtful decisions.
But when was the last time someone reviewed how all those decisions affect one another?
Without coordination, even good decisions can create a “financial Frankenstein,” or a collection of carefully selected parts, stitched together over time, that doesn’t function as one cohesive plan.
Each piece may serve a legitimate purpose. The missing element is often someone making sure everything supports the same goals.
How a Plan Becomes a Patchwork
Most people build their financial lives gradually. You open a retirement account at your first job, buy insurance when your family grows, and hire an attorney when you need estate documents. A business opportunity or property purchase introduces another specialist.
Each addition addresses something important at the time. Years later, though, you may have several professionals working from different information, different assumptions, and different versions of what you want to accomplish.
Your CPA may know you’re preparing to sell your business. Your investment advisor may be planning around a retirement date you’ve since changed. Your estate attorney may have documents that reflect neither development.
Everyone can be doing their individual job well while the overall plan drifts.
Where Good Decisions Can Collide
The trouble often appears at the seams, where one area of planning meets another.
Investments and taxes.
An advisor recommends a Roth conversion while another professional is helping you manage income from a business sale. Converting previously untaxed retirement dollars generally creates taxable income. Before proceeding, someone needs to evaluate the conversion alongside everything else happening that year.
Estate documents and beneficiary forms.
You update your estate plan to reflect your wishes, but the beneficiary designations on retirement accounts or insurance policies remain unchanged. Those designations can direct assets outside the instructions in your estate documents, potentially undermining the intended result. Reviewing both together matters.
Business planning and personal cash flow.
You develop a succession strategy that transfers ownership to the next generation. But has anyone connected the payment terms with your retirement spending needs, investment resources, and tax obligations? A workable transition for the business also needs to support the life you expect afterward.
But each of these situations share a problem: a decision was evaluated without enough attention to what surrounded it.
Who Is Responsible for the Connections?
Having several professionals can be valuable. Financial planning, tax advice, estate law, and insurance require different expertise.
Coordination gives those specialists a shared understanding of what they are helping you accomplish. It also requires clear responsibility.
If you’re the person forwarding emails, repeating conversations, and deciding which details each professional needs, you may have become the coordinator by default. That puts you in the position of spotting connections you hired specialists to understand.
A useful question to ask your team:
Who is responsible for reviewing how these recommendations work together?
The answer should identify a person and a process.
Bring the Plan Back Together
Fixing a financial Frankenstein doesn’t necessarily mean starting over. Much of what you have may still serve you well. The first step is understanding where the connections need attention.
Ask for a coordinated review, especially before a major transaction or life change. That review should establish:
-
A shared picture. With your authorization, professionals should have the relevant information about your assets, obligations, goals, and decisions already underway.
-
A designated lead. Someone should organize the review, track unresolved questions, and follow up across disciplines.
-
A common timeline. Discuss upcoming sales, withdrawals, ownership changes, and other significant moves before they happen.
-
Written responsibilities. Record who will handle each action and when the team will revisit the plan.
At Prestige Advisors, we work with your CPA, attorney, and other professionals to help connect the decisions shaping your financial life. With your authorization, that collaboration helps bring tax strategy, investments, insurance, estate considerations, and business planning into the same conversation.
If you already have the pieces in place, the next step may be a conversation about how they fit. Ask your team to walk through one major goal together — and explain how each part of your plan helps you get there. Send us an email at hello@prestigeadvisors.com or schedule a free conversation today!
Disclosure: This content is for educational and informational purposes only. It does not constitute investment, financial, tax, or legal advice, and nothing here should be interpreted as a recommendation to buy or sell any security or pursue any specific strategy. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Tax laws are complex and apply differently to each person’s situation. Consult your own qualified tax, legal, and financial professionals before making any decisions.